
Accra, Ghana//-First Atlantic Bank PLC, which recently listed on the Ghana Stock Exchange (GSE), today assured the investing public it would continue to prioritise technology as a key driver of its growth and digital banking innovation in the country.
The bank also pledged to continue its rough ongoing investments in secure, reliable infrastructure and customer-focused solutions, thereby enhancing the bank’s customer experience.
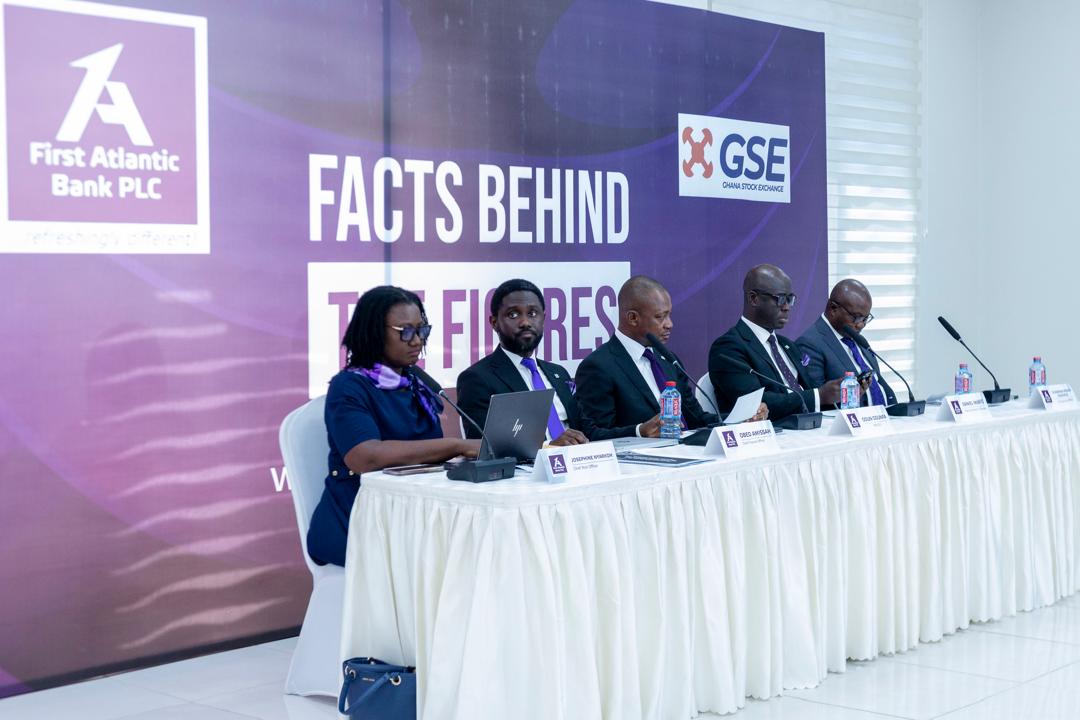
Senior officials of First Atlantic Bank PLC gave the assurance when they took their turn on the Facts Behind The Figures organised by the GSE for listed companies.
According to them, Atlantic FlexiPay Ltd, formerly FlexiPAY, which was established as a standalone fintech within the First Atlantic Bank Group, with 91,500 subscribers could be expanded.
Its focus is on improving platform stability, expanding local merchant acquisition and strengthening ecosystem integration, while ensuring regulatory compliance and supporting sustainable growth.
These efforts reinforce the bank’s commitment to delivering seamless, secure and efficient banking services, they said.
For the remainder of 2026, the bank assured that it would continue to focus on deploying its expanded deposit base efficiently to improve yields while maintaining prudent risk levels.
With loans and advances of GHS2.5 billion against customer deposits of GHS19.0 billion, the bank has significant capacity to expand lending to businesses and individuals while complying with the Bank of Ghana’s new NPL directive, they told shareholders, brokers and the investing public.
Strong performance
Speaking at the event, the Chief Executive Officer of First Atlantic Bank PLC, Odun Odunfa, said: “Our performance in the first nine months of 2026 reflects the resilience of our business”.
He continued that strong customer confidence has supported deposit growth, enabling us to extend credit to more businesses and households while making everyday transactions more accessible and convenient.
“At the same time, we have maintained cost discipline while continuing to invest in the people, technology and infrastructure needed to support sustainable growth”, Mr Odunfa added.
He also noted that total assets increased by 39% year-on-year to GHS21.8 billion, supported by strong customer deposit mobilisation and continued balance sheet expansion.
Customer deposits grew by 37% to GHS19.0 billion, reflecting sustained customer confidence and providing the bank with a stable funding base to support future lending and investment activities, according to him.
The bank’s loans and advances recorded robust growth of 67% year-on-year to GHS2.5 billion, demonstrating the bank’s continued support for the real economy, while investment securities rose by 44% to GHS5.2 billion. Shareholders’ funds increased by 33% to GHS2.4 billion.
Net interest income rose by 37% to GHS524 million, supported by strong growth in earning assets and a 33% reduction in interest expense as funding costs eased. Net fee and commission income grew by 55% to GHS200 million, reflecting increased transaction volumes and growing customer activity, and reinforcing the Bank’s increasingly diversified revenue base.
The bank recorded profit before tax of GHS386 million, a 4% increase over the corresponding period in 2025, and profit after tax of GHS261 million, up 3%.
Operational Efficiency
Operating income grew by 31% to GHS 821.7 million, outpacing the 23% increase in operating expenses, which reflected continued investments in people, technology and operating infrastructure to support long-term growth.
Consequently, the cost-to-income ratio improved to 53.5% from 56.7% in Q3 2025, demonstrating continued cost discipline amid business expansion.
Operating Environment
Despite the declining interest rate environment, the bank recorded a 3% growth in interest income, driven by increased volumes of loans and investment securities, which more than offset the impact of lower yields.
Interest expense, on the other hand, declined significantly by 33% to GH¢246 million, reflecting lower funding costs and improved cost efficiency.
The bank’s balance sheet also strengthened considerably during the period, with customer deposits growing by 37% to GH¢19.0 billion and shareholders’ funds increasing by 34% to GH¢2.4 billion.
These results demonstrate the bank’s ability to sustain growth, optimise funding costs and strengthen its financial position despite the challenging interest rate environment.
The bank enters the final quarter of the year with a larger, stronger balance sheet and a solid foundation for continued growth.
Looking forward, the management of the bank assured that they would also prioritise sustaining fee income growth, keeping expense growth below income growth, and strengthening business performance to gain market share in Liberia.
